Boost Your Wealth and Shield Your Future with HDFC Life Sampoorn Nivesh Plus.
Dive into Our ULIP Selection

Life coverage is available

Past 5 year returns of 32.39%~

Save tax up to Rs.46,800/-10

Multiple fund options


ULIP or Unit Linked Insurance Plan offers a unique combination of life insurance coverage and investment opportunities in a single plan. The life insurance coverage provides financial protection for your loved ones and the investment component helps you grow your wealth over the long-term.
ULIPs come in various types, depending on investment goals, fund options and how premiums are paid. Here’s a breakdown of the different types of ULIPs:
Wealth Creation
Child Education
Suitable for – Parents planning for children's education
Retirement
Equity linked
Debt linked
Hybrid/balanced
Level Cover
Increasing Life Cover
Single Premium
Regular Premium
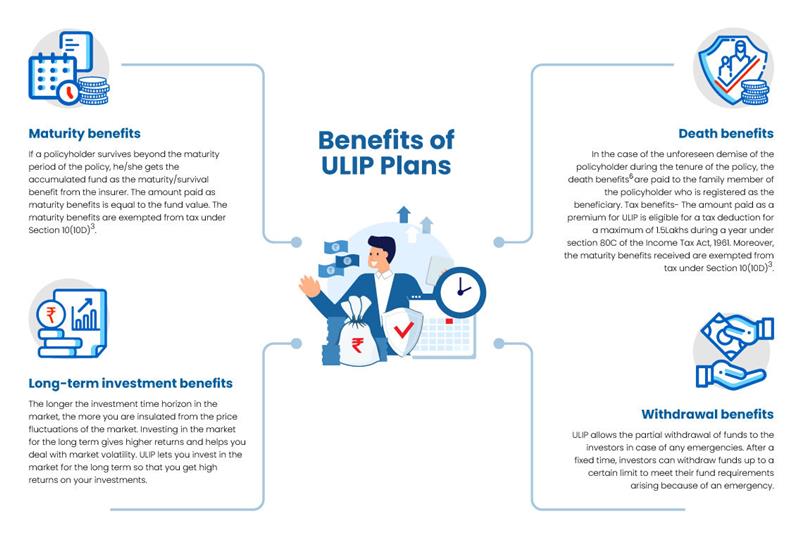
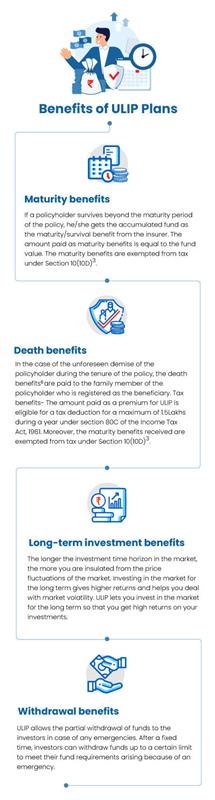
Here is the breakdown of the primary benefits of ULIP plans:
ULIPs give you the opportunity to invest in different types of funds – equity, debt and hybrid as per your risk appetite and personal financial goals. With ULIPs you can take advantage of the power of compounding to create wealth over time.
...Read More
If the policyholder passes away during the policy term, the beneficiaries receive the sum assured or the fund value, whichever is higher. The family feels financially secure with this payout.
...Read More
ULIPs being a life insurance product helps you save tax on the premiums you have paid under section 80C, get tax-free maturity benefit under Section 10(10D) subject to the conditions as prescribed and switch funds tax-free.
...Read More
ULIPs are designed for long-term investments with a lock-in period of 5 years. Investing regularly and for a longer time horizon (5+ years) protects your investment from the market ups and downs to eventually generate high returns.
...Read More
ULIPs are an effective financial instrument to save for your financial goals – child’s education, retirement planning, buying a home etc.
...Read More
ULIPs allow partial withdrawal after the 5-year lock-in period, providing easy access to cash during emergencies. However, there is a cap on the withdrawal based on the fund value or the policy terms and conditions.
...Read More
ULIP plans offer a wide range of flexibility in terms of – fund switches (to adapt to changing market conditions), premium redirections, top-ups (to increase your contributions). These inherent features make ULIP a very customisable financial product.
...Read More
To enhance the financial protection of ULIPs you can choose to opt for riders such as critical illness rider, waiver of premium rider (include for child plans), live well rider etc.
...Read More
You can easily keep track of your fund performance, NAV and other policy details of your ULIP.
...Read More
Optimizing your ULIP's investment returns is essential for building long-term wealth and securing your financial future. In a ULIP, market-linked returns are the engine that drives your fund's growth, helping you achieve significant gains over time. Higher returns can amplify your savings, providing you with the financial flexibility to meet future goals such as retirement, education, or major life milestones. Selecting a ULIP with strong growth potential is key to ensuring that your investment works hard for you. To explore the best ULIP options and find the plan that aligns with your financial aspirations, click the tabs below.
ARN - MC/02/25/21389
A ULIP is a financial instrument that provides the dual benefit of comprehensive life coverage and wealth growth. Additionally, a policyholder can avail various ULIP tax benefits. A ULIP plan offers the following tax benefits:
You can claim deductions of up to Rs. 1.5 Lakh every year on premiums applicable under Section 80C3 of the Income Tax Act of 1961, subject to the availability of terms and conditions
Maturity benefits existing under the ULIP policy are exempted under Section 10(10D)3 of the Income Tax Act, 1961.
The life coverage amount paid out to the nominee under certain unfortunate incidents is subject to tax exemption under Section 10(10D)3 of the Income Tax Act. This thereby ensures complete payout to families and financial support during times of need.
UIN: 101A038V01
A Linked, Non-Participating Pure Risk Premium, Individual Life rider where you can get additional income benefits over and above your Sum Assured in the event of total permanent disability due to an accident.
DOWNLOADUIN: 101A037V01
A Linked, Non-Participating Pure Risk Premium, Individual Life/Health rider where you can get protected with a proportion of Rider Sum Assured in case of accidental death or partial/total disability due to accident or diagnosed with Cancer.
DOWNLOADUIN: 101A034V01
A Linked, Non-Participating Savings/Pure Risk Premium, Individual Health rider where you can get lump sum benefit equivalent to Rider Sum Assured on diagnosis of any of the covered 60 Critical Illnesses or benefit as a proportionate of the Rider Sum Assured on diagnosis of Early Stage Cancer / Major Cancer depending on the plan option chosen.
DOWNLOADUIN: 101A035V01
A Linked, Non-Participating, Individual Pure Risk Premium, Life/Health rider where you can get Waiver of Premium for the base policy premium and premiums of any other additional riders, in case of death, disability or diagnosis of any listed critical illnesses of the Rider Life Assured. Enjoy continued policy benefits even in case of life's eventualities.
DOWNLOADULIP stands for Unit-Linked Insurance Plans. It offers both insurance and investment avenues.
Depending on one's financial goals and risk appetite, investors can choose between equity, debt and/or other instruments to invest in. Funds under ULIP plan include a number of instruments. The ratio of debt to equity held is different for every fund. A ULIP has multiple such funds to choose from.
The returns on ULIP plans can vary because the investor gets to choose the combination of equity, debt, hybrid funds in their investment. ULIPs with less risk exposure tend to offer lower returns compared to high-risk equity ULIPs.
Insurance providers collect policyholders’ capital and invest it in funds of their choice. After the amount is invested, the total is divided into 'units' of a specific value. These 'units' are allocated to the investor according to the amount invested by them.
Fund value simply is the net asset value or NAV of a fund on the given day, multiplied by the number of units held by the investor.
For example, if a fund's NAV is ₹ 50 and an investor holds 3000 units of the fund, the fund value for the investor will be ₹ 50 x 3000 = ₹ 1,50,000.
Comparing the initial and current NAV shows a fund’s progress and returns earned.
The main feature of ULIPs is that they are insurance plans that help build long-term wealth with their market-linked investment options. They offer a high return potential while also providing dual tax benefits, both on premium payments and on payouts/sum received after maturity.
As per Income Tax Act, 1961. Tax benefits are subject to changes in tax law.
Investors that have been regular in their premium payments can opt for paying ‘top-up’ premiums, which are additional investments towards the plan. Investors can tap into the potential of a ULIP with good performance history and good returns with these extra premiums.
Yes. Policyholders can opt for a single premium ULIP plan which requires a one-time payment at the time of purchase of the policy, instead of regular premiums. After the maturity period, the policyholder receives the sum assured. Top-up premiums for these ULIPs may not be available during the first 5 years.
Yes, you can. The lock-in period for ULIPs is 5 years. If you plan to cancel/surrender the plan after 5 years, you will get the accumulated funds till the date of surrender. If you surrender before the lock-in period then discontinuance charges will be deducted and the balance amount will be paid to the policyholder after the completion of the 5 years lock-in period.
Most ULIP plans have a lock-in period of 5 years after which the policyholder can choose to withdraw a part of their fund, if the need arises. This is done by ‘cancelling’ some of the units held. There is a limit to the amount that can be withdrawn and it may vary across plans.
The entire fund value is paid to the policyholder if a ULIP plan is surrendered after the 5-year lock-in period. However, the process of surrendering the policy before 5 years is different. The amount will be paid to the policyholder only after the end of 5 years. However, the insurance provider will deduct discontinuance charges from the fund value. The balance is transferred to a Discontinued Policy (DP) fund and a fund management charge of not more than 0.5% is applied. The DP fund will earn interest over time to provide the minimum return guaranteed by the provider.
The fund value refers to the total value of the units a policyholder owns. In ULIP, investors can choose from a variety of schemes as per their risk appetite and financial goals. Fund value on a particular day can be calculated by multiplying the Net Asset Value (NAV) of a unit on that day to the number of units owned by a policyholder.
The time for which a policyholder cannot withdraw or liquidate the accumulated funds is called the lock-in period.
ULIP plans provide a variety of fund options for an investor to choose from. Ranging from aggressive to conservative ULIP plans, you can choose as per the market scenarios and your risk-taking ability. If you are risk-averse then you can choose conservative ULIP plans that invest in the debt market.
Interest earned on ULIPs is exempt from taxes if the annual premium is up to INR 2,50,000 per year. For annual premiums over the amount, the interest will attract Long-Term Capital Gains (LTCG) tax of 10%.
As per Income Tax Act, 1961. Tax benefits are subject to changes in tax law.
ULIPs provide both insurance and investment, making them a good financial tool to have in your portfolio. They allow flexible investment and give you control over fund allocation, enabling you to decide how and where money gets invested.
A Unit-Linked Insurance Plan is a type of investment plan that also provides an insurance component.
Mutual funds are investments that pool together resources from several investors. They do not have an insurance component.
A SIP or Systematic Investment Plan refers to a method of investment in mutual funds.
If you discontinue your policy after five years, you will receive the policy's surrender value.
The sum assured refers to the life insurance payout the policyholder’s beneficiary receives as the death benefit.
Yes, ULIPs today have a lock-in period of five years, so policyholders are free to withdraw their ULIP plan after this time, though it is not encouraged. You can make a partial withdrawal during some financial emergencies as long as the amount you withdraw does not exceed a percentage of the total premiums paid.
No, you cannot withdraw your ULIP plan before the five-year lock-in period. If you surrender it after three years, you will not receive any of the funds payable until after the lock-in period ends.
If you surrender your ULIP plan after five years, the surrender value does not attract any taxes, subject to prevailing tax laws.
The maturity benefit of a ULIP plan is tax-free only if the total premiums paid per year do not exceed INR 2,50,000. If the premiums exceed INR 2,50,000, the maturity amount will attract a 10% LTGC tax3
ULIPs are market-linked products, so the returns vary depending on market fluctuations, the plan tenure, and your selected funds. You must decide on the best investment avenues based on previous performance, projected returns, and personal financial goals.
Yes, it is possible to surrender a ULIP plan before the five-year lock-in period ends, but it is not advisable. You will not receive any payouts until after the lock-in period ends if you surrender your ULIP before five years. Additionally, you could have to pay a surrender fee and tax on the investment amount.
A ULIP can be better than an FD if you have a higher risk tolerance and the aim of getting market-linked returns. ULIP ensures the safety of money by providing comprehensive life coverage. It also provides chances of earning high returns through investing.
With a systematic investment plan and market-linked returns, you can make money through ULIPs. With ULIP, you can generate wealth to achieve your long-term goals of meeting your child's expenses, owning a dream house, and more.
Our expert will assist you in buying a right plan for you online.
Reach us between 9 AM - 10 PM IST.
For existing policy related assistance, click here.
A certified expert of HDFC Life will help you.
*99.72% Claim Settlement Ratio For FY 2025-2026
~4.6 Cr. Number Of Lives Insured For FY 2025-2026
Disclaimer: By submitting your contact details, you agree to HDFC Life's Privacy Policy and authorize ...Read More
*99.72% Claim Settlement Ratio For FY 2025-2026
~4.6 Cr. Number Of Lives Insured For FY 2025-2026
I was surprised to see how detailed and informative the information was served to me. It just made my online buying experience worth the time.
Thank you HDFC Life team, you have lived upto your expectation. Your simple claim settlement process just made my life easier.
It was a seamless online policy purchase process for me, thanks to HDFC Life.
Thank you team for your support throughout the claim process and I really appreciate the efforts of everyone involved
I was really delighted with the online buying experience. Upto date information and online guidance really helped me. Tx
My experience with HDFC Life has been really good. I specifically remember the process of online onboarding it was really smooth and hasslefree
Appreciate you keeping me upto date with your weekly newsletters. Tx
The online buying process was simple and quick. Good guidance by the HDFC Life team.
The online payment process was smooth and I was able to complete my premium payment easily!
HDFC Life representatives explained the product well and helped me buying completing the process online reall quick. Thank you!
Reviewed by Life Insurance Experts
We at HDFC Life are committed to offer innovative products and services that enable individuals live a ‘Life of Pride’. For over two decades we have been providing life insurance plans - protection, pension, savings, investment, annuity and health.
In unit linked policies, the investment risk in the investment portfolio is borne by the policyholder. The Unit Linked Insurance products do not offer any liquidity during the first five years of the contract. The policyholders will not be able to surrender/withdraw the monies invested in Unit Linked Insurance Products completely or partially till the end of fifth year.
Life Insurance Coverage is available in this product. The unit linked insurance products do not offer any liquidity during the first five years of the contract. The policyholder will not be able to surrender/withdraw the monies invested in unit linked insurance products completely or partially till the end of fifth year. Unit Linked Funds are subject to market risks and there is no assurance or guarantee that the objective of the investment fund will be achieved. The premium shall be adjusted on the due date even if it has been received on advance.
Unit Linked Life Insurance products are different from the traditional insurance products and are subject to the risk factors. The premium paid in Unit Linked Life Insurance policies are subject to investment risks associated with capital markets and the NAVs of the units may go up or down based on the performance of fund and factors influencing the capital market and the insured is responsible for his/her decisions. The name of the company, name of the brand and name of the contract does not in any way indicate the quality of the contract, its future prospects or returns. Please know the associated risks and the applicable charges, from your insurance agent or the intermediary or policy document of the insurer. The various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns.
1. Opt for Settlement Option to receive maturity benefit in periodical installments.
3. Tax benefits & exemptions are subject to conditions of the Income Tax Act, 1961 and its provisions. Tax Laws are subject to change from time to time. Customer is requested to seek tax advice from his Chartered Accountant or personal tax advisor with respect to his personal tax liabilities under the Income-tax law.
6. Death Benefit under the product - Sum Assured less all withdrawals made during the two year period immediately preceding the death of the Life Assured. Unit Fund Value based on the number of units and the Unit Price of the fund is also payable. The Minimum death benefit will be at least 105% of the total premiums paid.
8. Assured maturity benefit will be paid only on policy maturity provided all due premiums have been paid and will not apply on death or surrender.
10. Save 46,800 on taxes if the insurance premium amount is Rs.1.5 lakh per annum and you are a Regular Individual, Fall under 30% income tax slab having taxable income less than Rs. 50 lakh and Opt for Old tax regime
13. This is subject to underwriting norms.
##Individual death claim settlement ratio by number of policies as per audited annual statistics for FY 2023-24.
~ This is the return of the benchmark index fund and not indicative of HDFC Life Top 300 Alpha 50 fund performance (SFIN - ULIF07828/02/25Alpha300Fd101). Source: https://www.nseindia.com/
**The returns mentioned is the 5-year benchmark return percentage of Nifty Alpha 50 index data as of April 30, 2025, and is not indicative returns of HDFC Life’s Top 300 Alpha 50 fund(SFIN:ULIF07828/02/25Alpha300Fd101) Source: https://www.niftyindices.com/Factsheet/Factsheet_Nifty_Alpha50.pdf
* Online Premium for HDFC Life Sampoorn Nivesh Plus policy (UIN: 101L180V01) under the Classic Plus Benefits Plan assume an 8% annualized return over a 20-year policy term with a 20-year premium-paying period; please note that these assumed returns are not guaranteed and do not represent minimum or maximum outcomes, as actual performance will depend on various factors including future investment performance. Some benefits under this plan are guaranteed, while others are variable and contingent on the insurer’s future performance in the life insurance business, and the calculations vary based on the selected death benefit amount: for a benefit of Rs. 1,000,000, the the death benefit value is Rs. 11,52,960; for benefits of Rs. 2,000,000, Rs. 3,000,000, or Rs. 5,000,000, the death benefit value is Rs. 21,12,960; and for benefits of Rs. 8,000,000 or Rs. 10,000,000, the the death benefit value is Rs. 96,00,000. Premiums are paid on a regular, monthly basis and are exclusive of applicable taxes and levies, with an example monthly premium of Rs. 2,601 equating to approximately Rs. 86.70 per day. These illustrations are provided for informational purposes only and do not guarantee future performance.The calculations will differ for the remaining illustrations.
The Unit Linked Insurance products do not offer any liquidity during the first five years of the contract. The policyholders will not be able to surrender or withdraw the monies invested in Unit Linked Insurance Products completely or partially till the end of fifth year.
Unit Linked Life Insurance products are different from the traditional insurance products and are subject to the risk factors. The premium paid in Unit Linked Life Insurance policies are subject to investment risks associated with capital markets and the NAVs of the units may go up or down based on the performance of fund and factors influencing the capital market and the insured is responsible for his/her decisions. HDFC Life Insurance Company Limited is only the name of the Insurance Company, The name of the company, name of the contract does not in any way indicate the quality of the contract, its future prospects or returns. Please know the associated risks and the applicable charges, from your Insurance agent or the Intermediary or policy document of the insurer. The various funds offered under this contract are the names of the funds and do not in any way indicate the quality of these plans, their future prospects and returns.
HDFC Life Smart Protect Plan (UIN: 101L175V07) is a Unit Linked Non-Participating Individual Life Insurance Savings Plan, Life Insurance Coverage is available in this product.
HDFC Life Sampoorn Nivesh Plus (UIN No: 101L180V01) is a Unit Linked Non-Participating Individual Life Insurance Savings Plan, Life Insurance Coverage is available in this product.
HDFC Life Click 2 Wealth (UIN-101L133V03) is a Unit Linked Non-Participating Individual Life Insurance Savings Plan, Life Insurance Coverage is available in this product.
HDFC Life Click 2 Invest Plus (UIN: 101L191V01) is a Unit Linked Non-Participating Individual Life Insurance Savings Plan, Life Insurance Coverage is available in this product.

Registered Office: Lodha Excelus, 13th Floor, Apollo Mills Compound, N.M. Joshi Marg, Mahalaxmi, Mumbai 400 011. Tel No: (022)67516666.
The name/letters "HDFC" in the name/logo of the company belongs to Housing Development Finance Corporation Limited ("HDFC Limited") and is used by HDFC Life under an agreement entered into with HDFC Limited.
HDFC Life Click 2 Protect Super (UIN: 101N145V01) is a non linked, non participating, individual, pure risk premium/savings life insurance plan. Life Insurance Coverage is available in this product.
For more details on risk factors, associated terms and conditions and exclusions please read sales brochure carefully before concluding a sale.
ARN - MC/06/25/24483
 :1800-266-9777